
Weekly Outlook
What Happened This Week?
Global Markets
● The WTO raised its global goods trade growth forecasts to 3.9% for 2026 and 4.1% for 2027, supported by strong AI-related investment. AI-linked goods accounted for nearly half of trade growth in the first half of 2026.
● The WTO cut its forecast for services trade growth to 3.3% from 4.8%, citing disruptions to tourism and transport caused by the Middle East conflict.
● The IMF warned that the global economy faces mounting risks from energy shocks, rising public debt and the AI investment boom. Global public debt is projected to exceed 100% of GDP, while oil prices could remain elevated through 2027 even if the Gulf conflict ends soon.
Europe
● German industrial production rebounded 2.0% in August, beating expectations for a 0.5% increase after July’s 1.2% decline. Construction and mechanical equipment output supported the recovery, alongside inventory-building amid geopolitical uncertainty.
● German factory orders plunged 10.6% in August, far exceeding expectations for a 1.0% decline. A 61.5% drop in transport-equipment orders, including aircraft, ships, trains and military vehicles, drove the contraction.
● France’s economic outlook remains under pressure from political and fiscal uncertainty. Business investment fell 0.3% in Q2 after declining 0.8% in Q1, while public debt climbed to 119% of GDP, well above the EU’s 60% reference level.
● ECB Chief Economist Philip Lane said eurozone wage growth is not currently raising major inflation concerns. He also noted that uncertainty over AI-related job losses and competition from China could restrain workers’ pay demands.
● Lane warned that higher energy prices could weaken eurozone demand and reduce the need for further rate increases. Rising long-term bond yields have already tightened financial conditions, while lower government borrowing is expected to weigh on growth in 2027 and 2028.
● Eurozone retail sales rose 0.1% in August after falling 0.6% in July, but spending momentum remains subdued. Automotive fuel sales dropped 1.9% as higher crude prices added pressure on consumers.
United States
● Fed officials remain divided over the timing of further tightening. St. Louis Fed President Alberto Musalem said rates may need to rise over the next six to nine months to bring inflation back towards 2%, while meeting minutes showed broad support for another increase this year but no clear urgency to act in October.
● New York Fed President John Williams and Fed Vice Chair Philip Jefferson signalled that policymakers could afford to wait for more data. Following a weaker-than-expected jobs report and dovish comments, market-implied odds of an October hike fell sharply.
● The ISM services PMI eased to 54.9 in September from 55.4 in August, indicating slower expansion. However, the services prices index climbed to 74, its highest level since July 2022, as fuel costs and supply-chain constraints continued to push up expenses.
● U.S. household spending increased 6.1% year-on-year through August, supported by both higher prices and greater purchasing volumes. However, the saving rate has fallen to 4.1% and consumer debt is at record levels, raising concerns about the sustainability of spending.
● Thirty-year fixed mortgage rates climbed to 7.4%, their highest level since November 2023. Higher borrowing costs are putting pressure on the housing market, with 21% of sellers cutting asking prices during the four weeks through September 20.
● Initial jobless claims fell to 197,000 in the week through October 3, marking a fifth consecutive weekly decline and coming in below expectations. Continuing claims, however, increased by 17,000 to 1.72 million.
India
● The Reserve Bank of India raised its benchmark repo rate by 25 basis points to 5.50%, its first increase in more than three years.
● The monetary policy committee voted 4–2 to shift its stance from neutral to calibrated tightening, with Governor Sanjay Malhotra indicating that rate cuts are unlikely in the near term.
● The Reserve Bank of India’s return to tightening highlights the growing challenge of balancing inflation control with economic growth as global energy costs and geopolitical uncertainty remain elevated.
This Week’s Market Movers
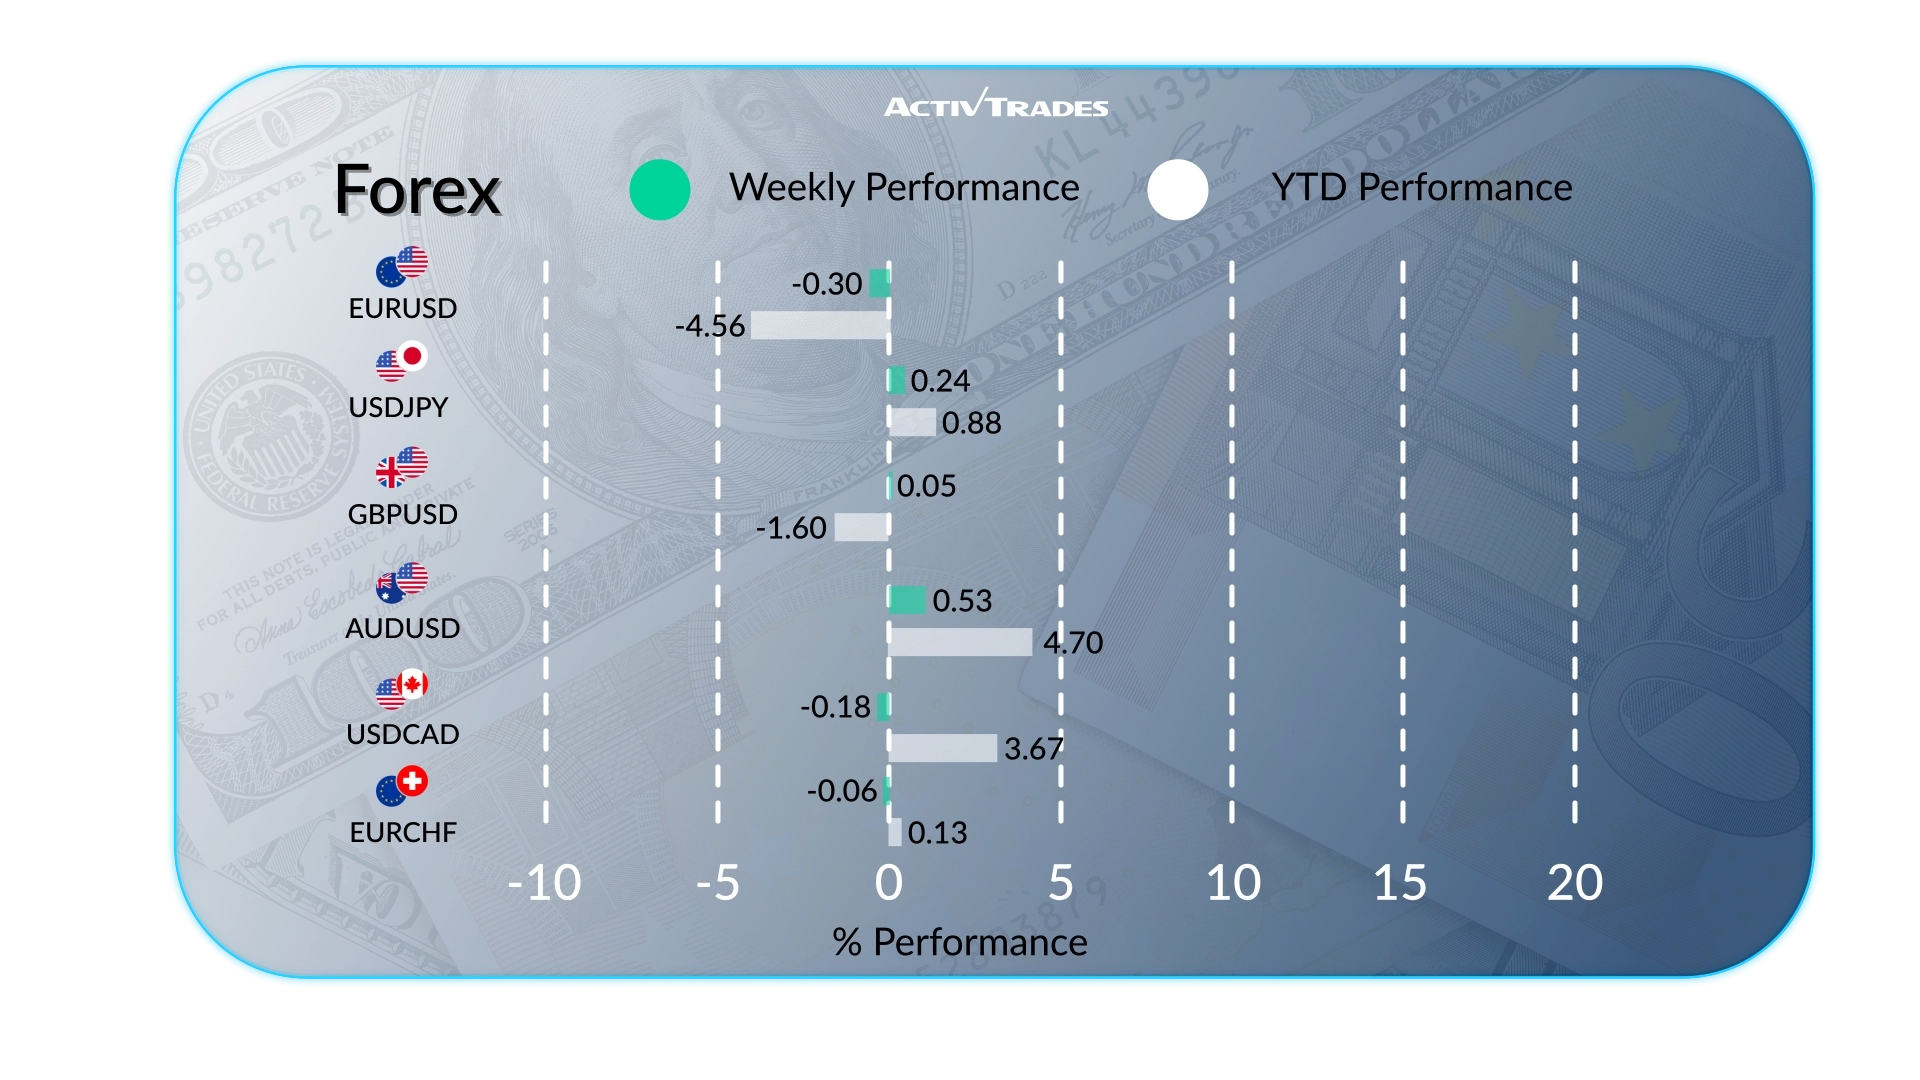
● The USD/RUB is up more than 1.8%.
● The EUR/RUB is up more than 1.6%.
● The AUD/EUR and the AUD/CHF are up more than 0.8%.
● The AUD/USD, the AUD/JPY and the AUD/CAD are up more than 0.7%.
● The GBP/USD is up more than 0.3%.
● The USD/BRL is down more than 4%.
● The EUR/USD is down more than 0.08%.
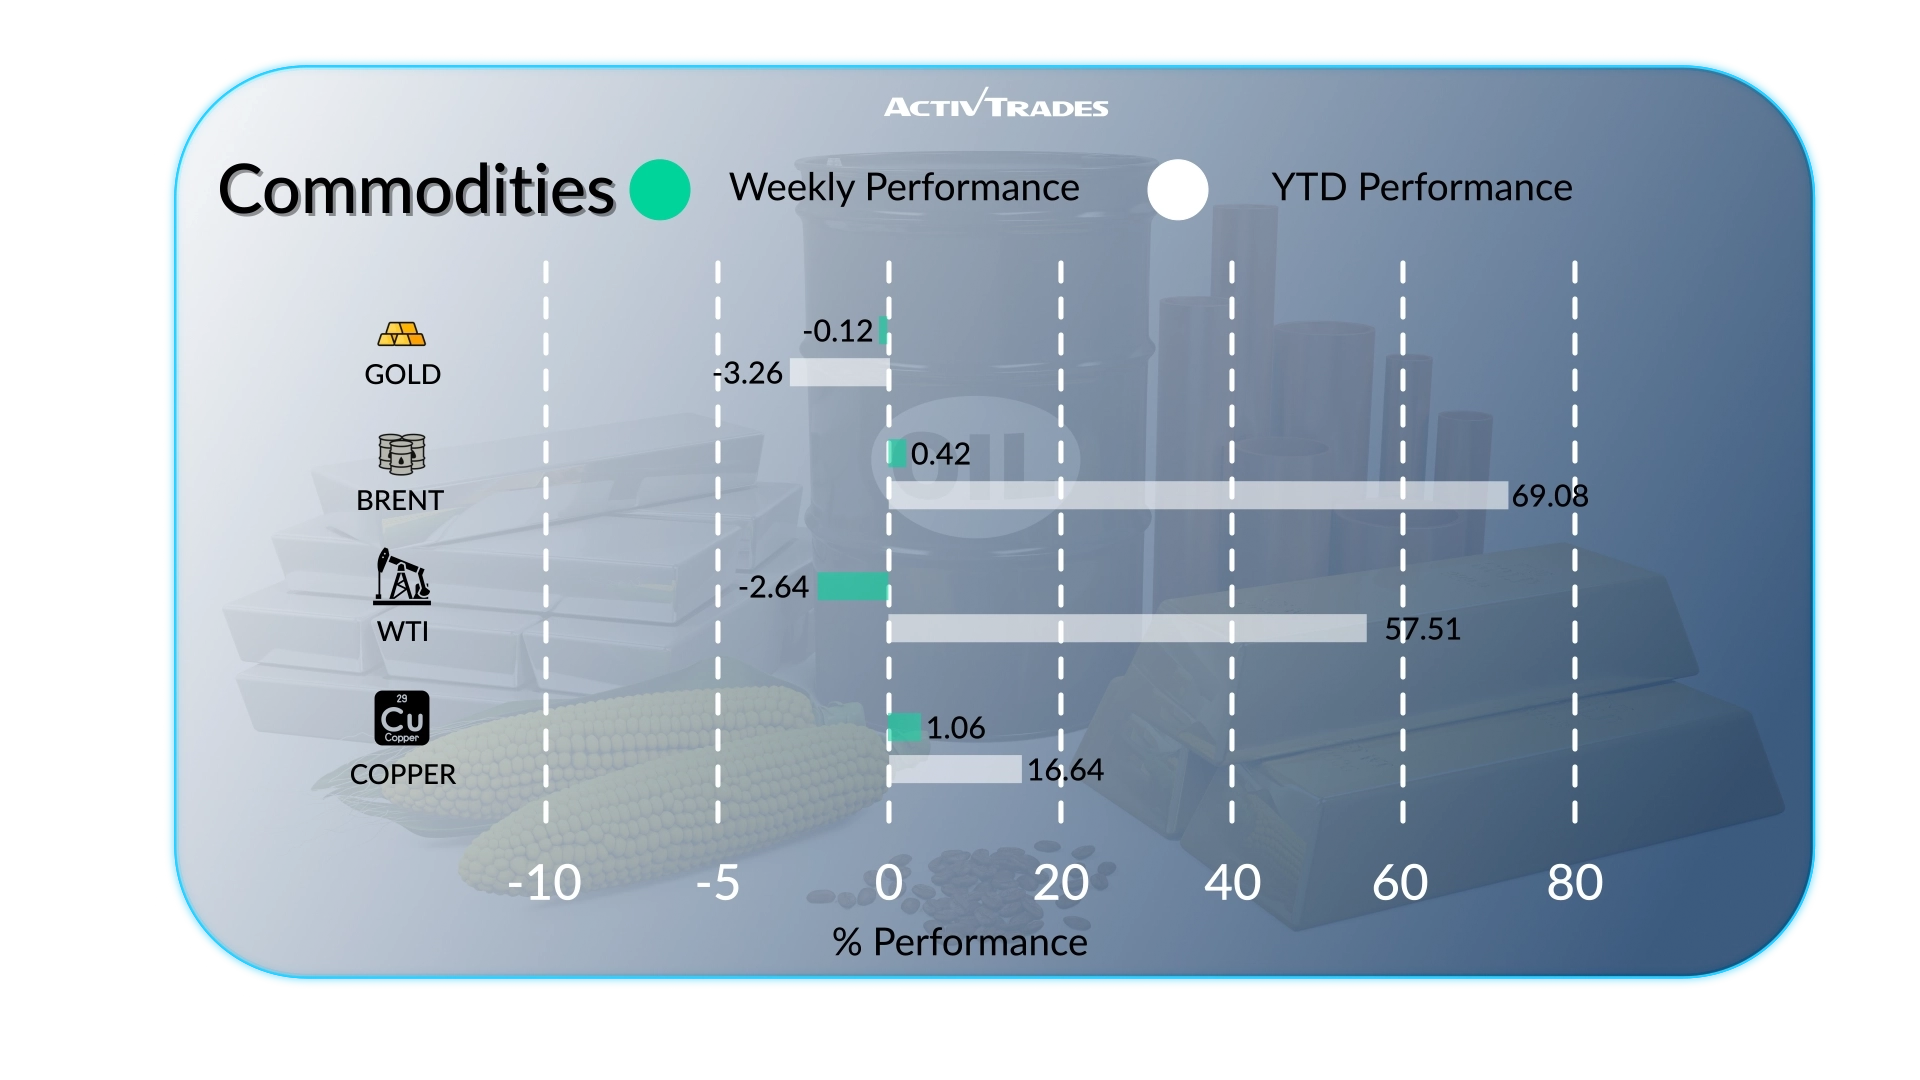
● Orange Juice and London Gas OIL prices are down more than 9.3%
● Oats prices are up more than 7.8%.
● Heating Oil prices are up more than 6.5%.
● US Cotton prices are up more than 5.7%.
● Aluminium prices are down more than 1.8%.
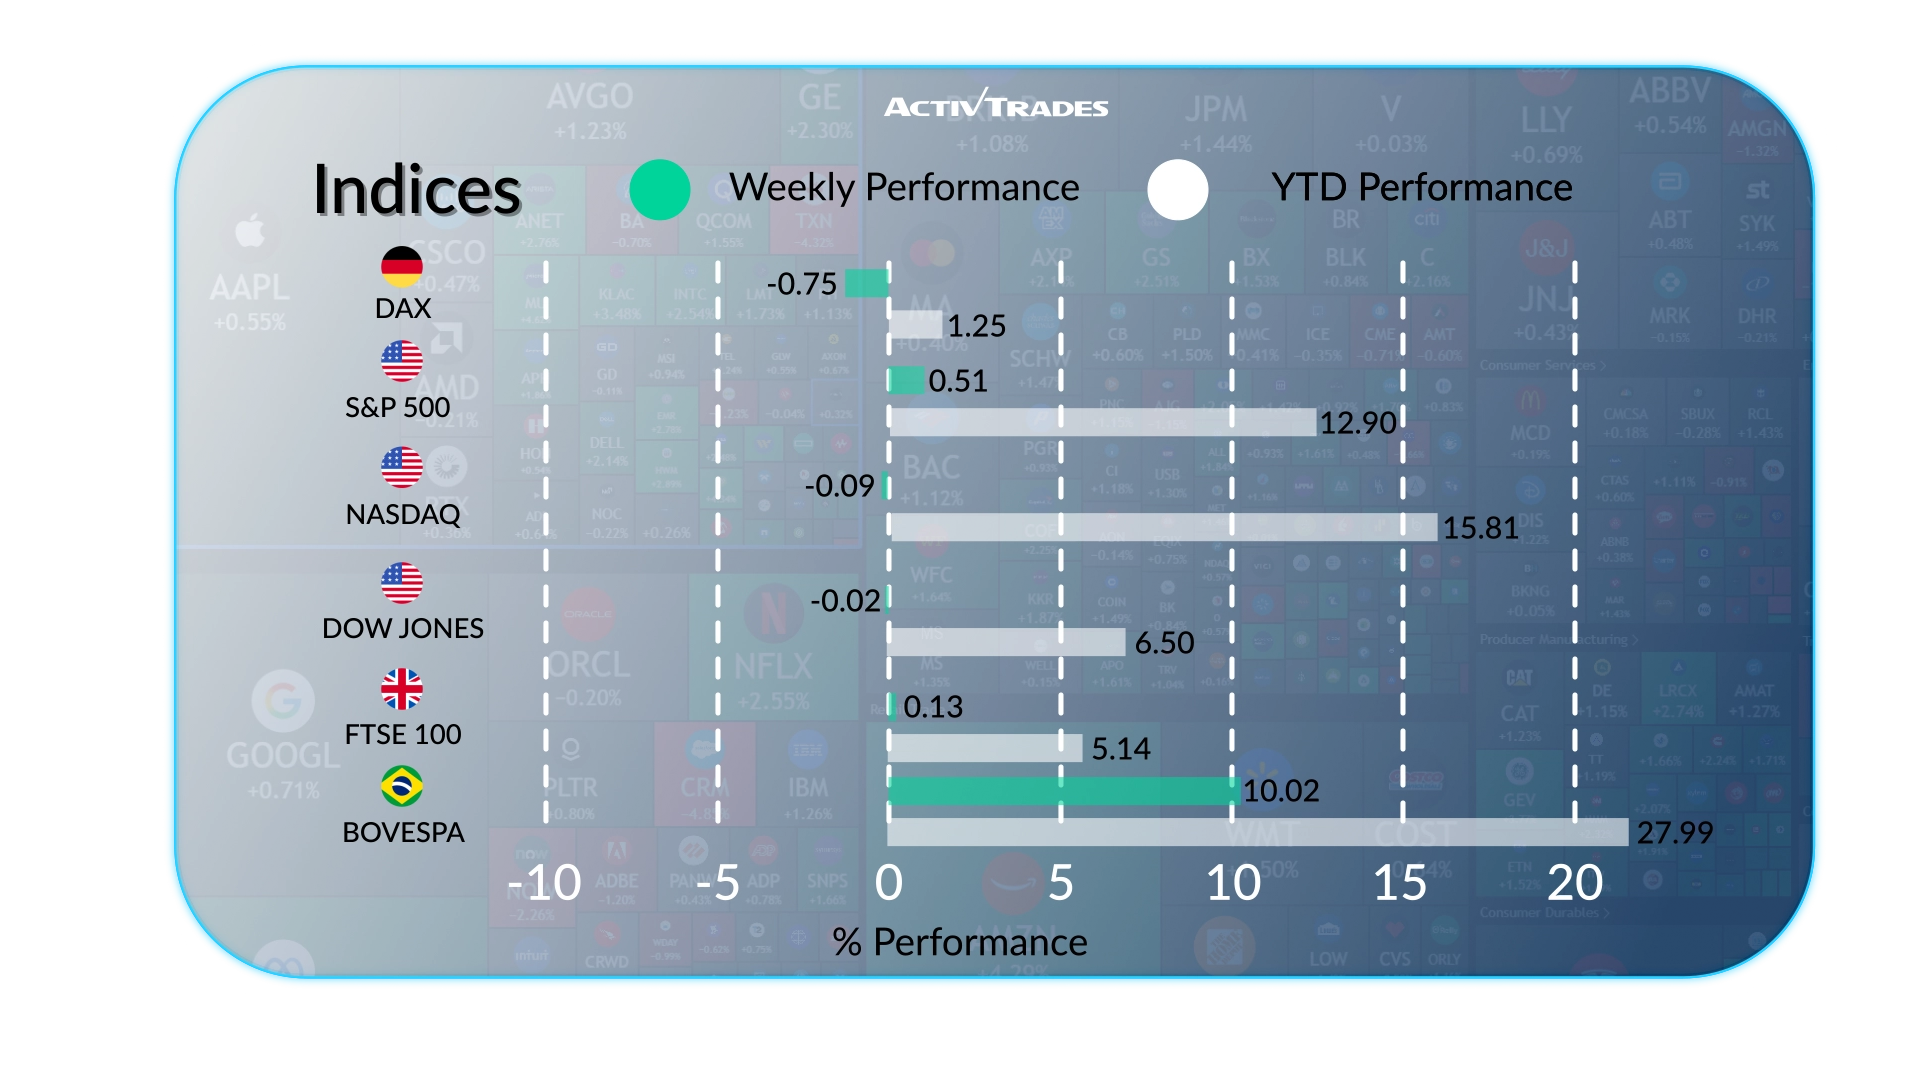
● The Bovespa index is up more than 10.6%.
● The VIX indices are down more than 5.6%.
Shares
Tops
● PTC: +32.27%
● Lamb Weston: +20.11%
● Ciena: +12.34%
● Vistra: +11.73%
● Autodesk: +10.55%
● Shopify: +10.38%
● Marathon Petroleum: +10.28%
Flops
● Seagate Technology: -18.06%
● Western Digital: -14.97%
● Intel: -10.77%
● Schneider Electric: -10.77%
Important Events to Follow
Tuesday 13 October
● 12:30 AM - Australian - NAB Business Confidence (September)
○ Previous: -8
○ Forecast: -9
● 12:30 AM - Australian - RBA Meeting Minutes
● 02:00 PM - American - Existing Home Sales (September)
○ Previous: 3.98M
○ Forecast: 3.97M
Wednesday 14 October
● 01:30 AM - Chinese - Inflation Rate YoY (September)
○ Previous: 0.8%
○ Forecast: 0.9%
● 03:00 AM - Chinese - Balance of Trade (September)
○ Previous: $119.1B
○ Forecast: $ 105.0B
● 03:00 AM - Chinese - Exports YoY (September)
○ Previous: 25%
● 03:00 AM - Chinese - Imports YoY (September)
○ Previous: 28.2%
● 12:30 PM - American - Core Inflation Rate YoY (September)
○ Previous: 2.4%
○ Forecast: 2.4%
● 12:30 PM - American - Inflation Rate YoY (September)
○ Previous: 3.4%
○ Forecast: 3.6%
Thursday 15 October
● 06:00 AM - UK - GDP MoM (August)
○ Previous: 0.4%
○ Forecast: 0.1%
● 12:30 PM - American - PPI MoM (August)
○ Previous: 0.4%
○ Forecast: 0.5%
● 01:30 PM - American - Retail Sales MoM (August)
○ Previous: 1.2%
○ Forecast: 0.1%
Friday 16 October
● 02:00 AM - UK - BoE Gov Bailey Speech
● 09:00 AM - European - Balance of Trade (August)
○ Previous: €14.2B
○ Forecast: €14.7B
Major Earnings Reports to Watch
Tuesday 13 October
● GOLDMAN SACHS
● JPMORGAN CHASE
● Citigroup
● Wells Fargo
● JOHNSON&JOHNSON
● UNITEDHEALTH
Wednesday 14 October
● Bank of America
● Blackrock
● Morgan Stanley
● ASML
Thursday 15 October
● Ericsson
● Bank of New York Mellon
● TSM
● US Bancorp
● Alcoa
Source: The Wall Street Journal, Investing, Trading Economics Calendar GMT, Reuters, TradingView and ActivTrades’ Data as of October 08, 2026
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and as such is to be considered to be a marketing communication.
All information has been prepared by ActivTrades (“AT”). The information does not contain a record of AT’s prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance is not a reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acting on the information provided does so at their own risk. Forecasts are not guarantees. Rates may change. Political risk is unpredictable. Central bank actions may vary. Platforms’ tools do not guarantee success.