
Weekly Outlook
What Happened This Week?
Global Markets
- Inflation risks are building as Middle East tensions push up energy costs, complicating central banks’ efforts to bring inflation under control. Businesses are increasingly passing higher input costs on to customers, raising the risk that price pressures become more persistent.
- Financial markets are reassessing interest-rate paths as stronger inflation readings and resilient labour markets increase expectations of further monetary tightening across several major economies.
United States
- S. housing starts fell 5.2% in September to an annualized 1.221 million, missing expectations for a rebound to 1.3 million. Building permits edged down 0.2% to 1.4 million, pointing to continued weakness in residential construction.
- Builder confidence deteriorated further, with the NAHB/Wells Fargo Housing Market Index dropping three points to 29 in October, its lowest level since June 2012. High mortgage rates, elevated construction costs and labour-market concerns are weighing on the sector. Some 43% of builders cut prices during the month, the highest proportion since 2020.
- The housing slowdown is increasingly uneven. In 33 of the 50 largest U.S. metropolitan areas, luxury home prices are rising faster than entry-level prices, according to First American Data and Analytics. High borrowing costs are sidelining many buyers, while affluent cash purchasers remain active, encouraging builders to prioritize higher-margin properties.
- Initial jobless claims declined by 6,000 to 194,000 in the week through October 17, reinforcing the picture of a resilient labour market. Continuing claims, however, increased by 25,000 to approximately 1.73 million in the week through October 10.
- Markets continue to anticipate further Fed tightening. Money markets assign a 15% probability to a 25-basis-point hike on October 28, while a December increase is fully priced in.
Eurozone
- Consumer confidence weakened for a second consecutive month as the Middle East conflict pushed energy prices higher. The European Commission’s flash indicator fell 1.1 points to -17.9 in October, below expectations of -17.0.
Germany
- The ZEW Indicator of Economic Sentiment fell 6.6 points to 28.1 in October, its first decline since April. High energy costs are weighing on household consumption and business investment, according to ZEW President Achim Wambach.
- The IMF expects Germany’s economy to grow 1.3% in 2026, up from 0.2% last year.
France
- French government bond yields climbed as investors remained concerned about budget negotiations, planned deficit reductions and the risk of further street protests. Commerzbank strategist Christoph Rieger said the unrest highlights broader concerns about rising global debt.
- France’s public debt has increased from around 89% of GDP in 2011 to approximately 119% today, according to BlackRock Investment Institute, adding to pressure on the government to restore fiscal stability.
United Kingdom
- UK inflation accelerated to 3.5% year on year in September from 3.1% in August, with higher global energy costs linked to the Iran war complicating the Bank of England’s efforts to reach its 2% target.
- Labour-market data strengthened expectations of a November rate hike. Annual regular-pay growth reached 3.7% in the three months through August, while unemployment unexpectedly fell to 4.7% from 4.9% in the previous three-month period.
- Money markets now assign a 93% probability to a 25-basis-point increase at the Bank of England’s November 5 meeting, with the key rate currently at 3.75%.
- Consumer confidence slumped, with the GfK index falling 11 points to -24 in October, its steepest monthly decline since April 2020. Deteriorating economic expectations and weaker intentions to make major purchases point to growing pressure on household spending.
Canada
- Canadian consumer inflation rose to 3.1% year on year in September, driven largely by a 27.8% surge in gasoline prices. Excluding gasoline, inflation eased to 2.2% from 2.4% in August, suggesting that underlying price pressures were more moderate.
- Business inflation expectations have increased sharply amid deteriorating trade relations and Middle East tensions, according to a Bank of Canada survey. More than half of surveyed firms plan to pass higher input costs on to customers, potentially strengthening the case for a rate increase at the October 28 policy meeting.
- Producer prices rose again in September, with the monthly increase reaching 2%, adding to concerns about cost pressures across the economy.
China
- China’s economy expanded 4.5% year on year in the third quarter, with exports providing much of the support. However, a prolonged property-market downturn and limited job security continue to weigh on household confidence.
- Fixed-asset investment fell 7.2% in the first nine months of the year compared with the same period in 2025. Property investment dropped 21%, highlighting the continuing drag from the real-estate sector.
Philippines
- The central bank raised its benchmark overnight reverse repurchase rate by 50 basis points to 5.50%, twice the increase expected by all 11 economists surveyed by The Wall Street Journal.
- The Bangko Sentral ng Pilipinas warned that inflation is likely to accelerate further as renewed Middle East tensions drive up energy prices.
Indonesia
- Bank Indonesia held its benchmark seven-day reverse repo rate at 5.75% but raised its overnight deposit facility rate to 5.0%. The move is intended to support the rupiah, attract foreign capital and keep inflation within the central bank’s target range.
Australia
- RBA Deputy Governor Andrew Hauser said the inflation outlook has deteriorated materially, warning that widespread cost pass-through by businesses could entrench inflation expectations.
- The RBA has raised interest rates four times this year, while inflation remains around 4.0%.
South Korea
- The Bank of Korea kept interest rates unchanged following two consecutive hikes.
This Week’s Market Movers
Forex
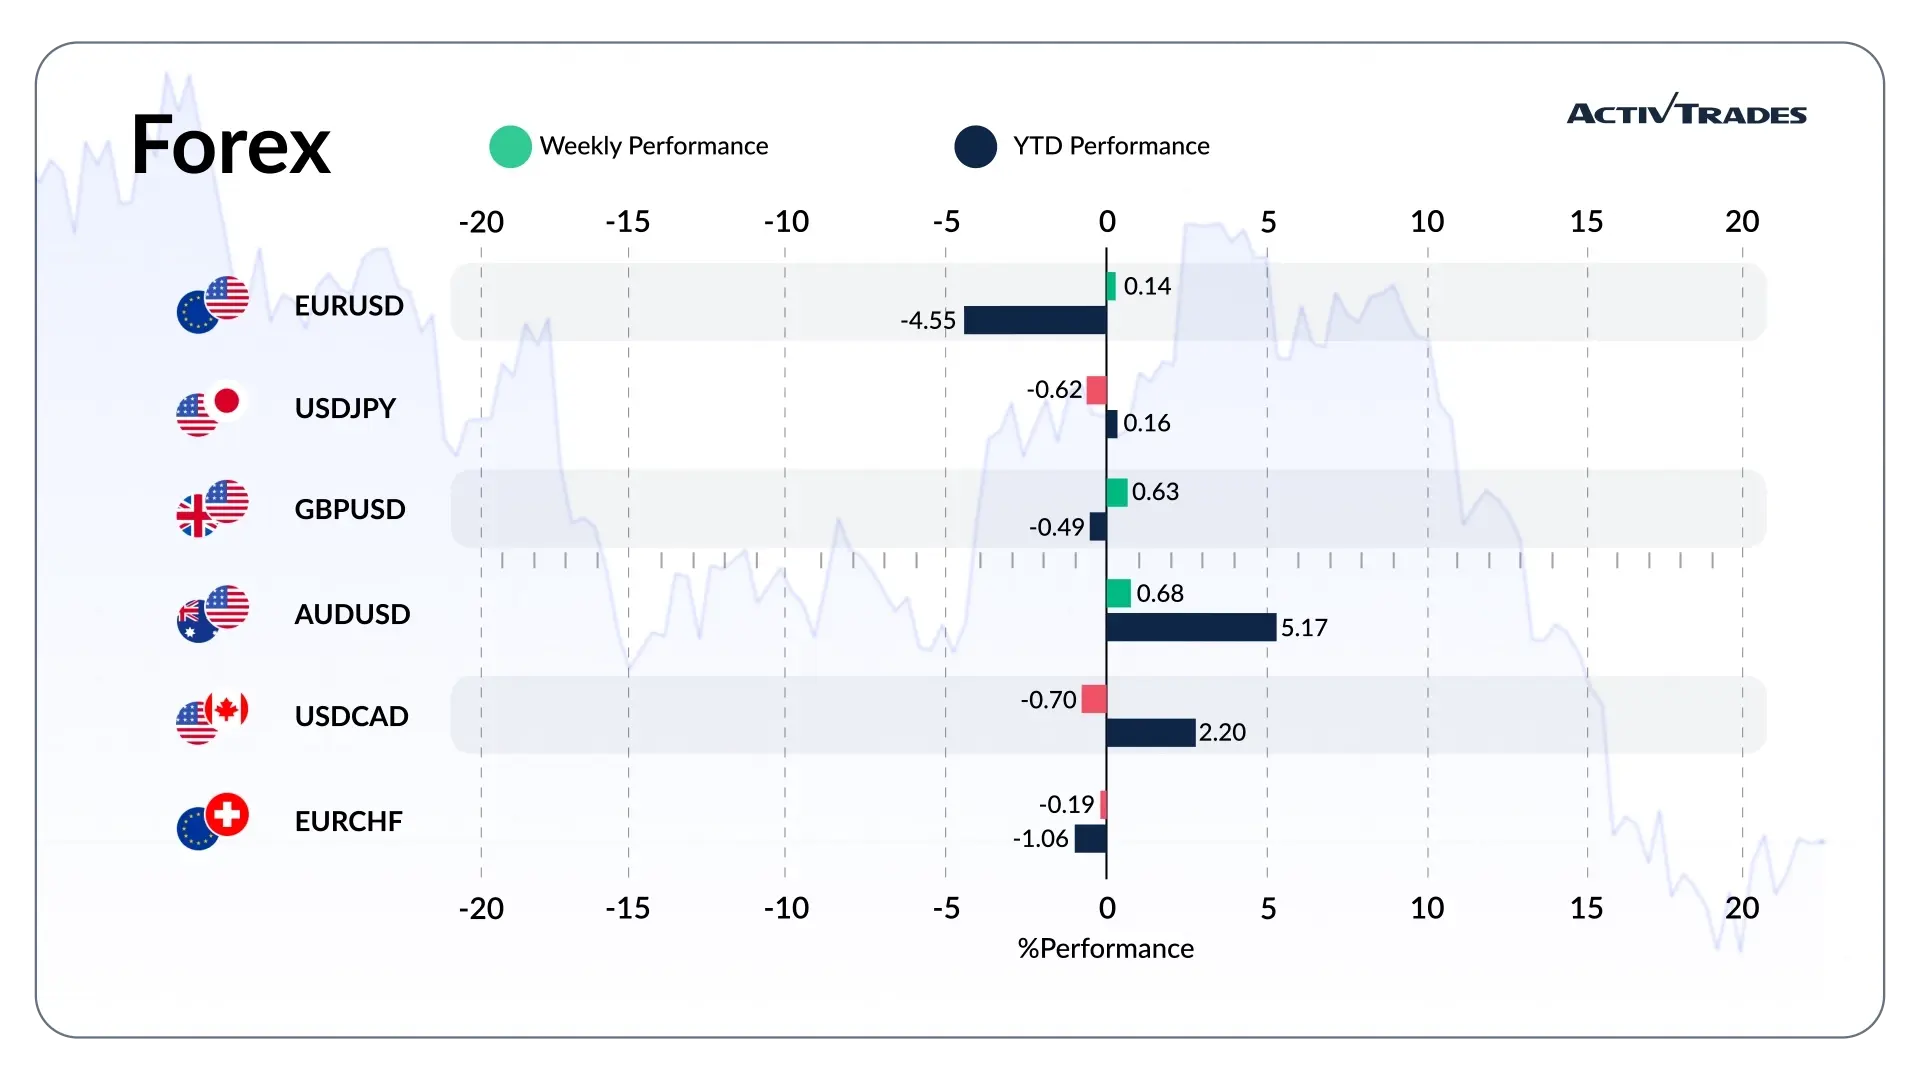
- The GBP/HUF is up more than 1.9%.
- The USD/MXN is up more than 1.7%.
- The EUR/MXN is up more than 1.6%.
- The AUD/EUR, the CAD/EUR and the NZD/EUR are up more than 1.3%.
- The AUD/USD and the NZD/USD are up more than 1.2%.
- The EUR/RUB and the USD/RUB are down more than 3%.
- The MXN/JPY is down more than 2.3%.
- The USD/CAD is down more than 1.2%.
Commodities
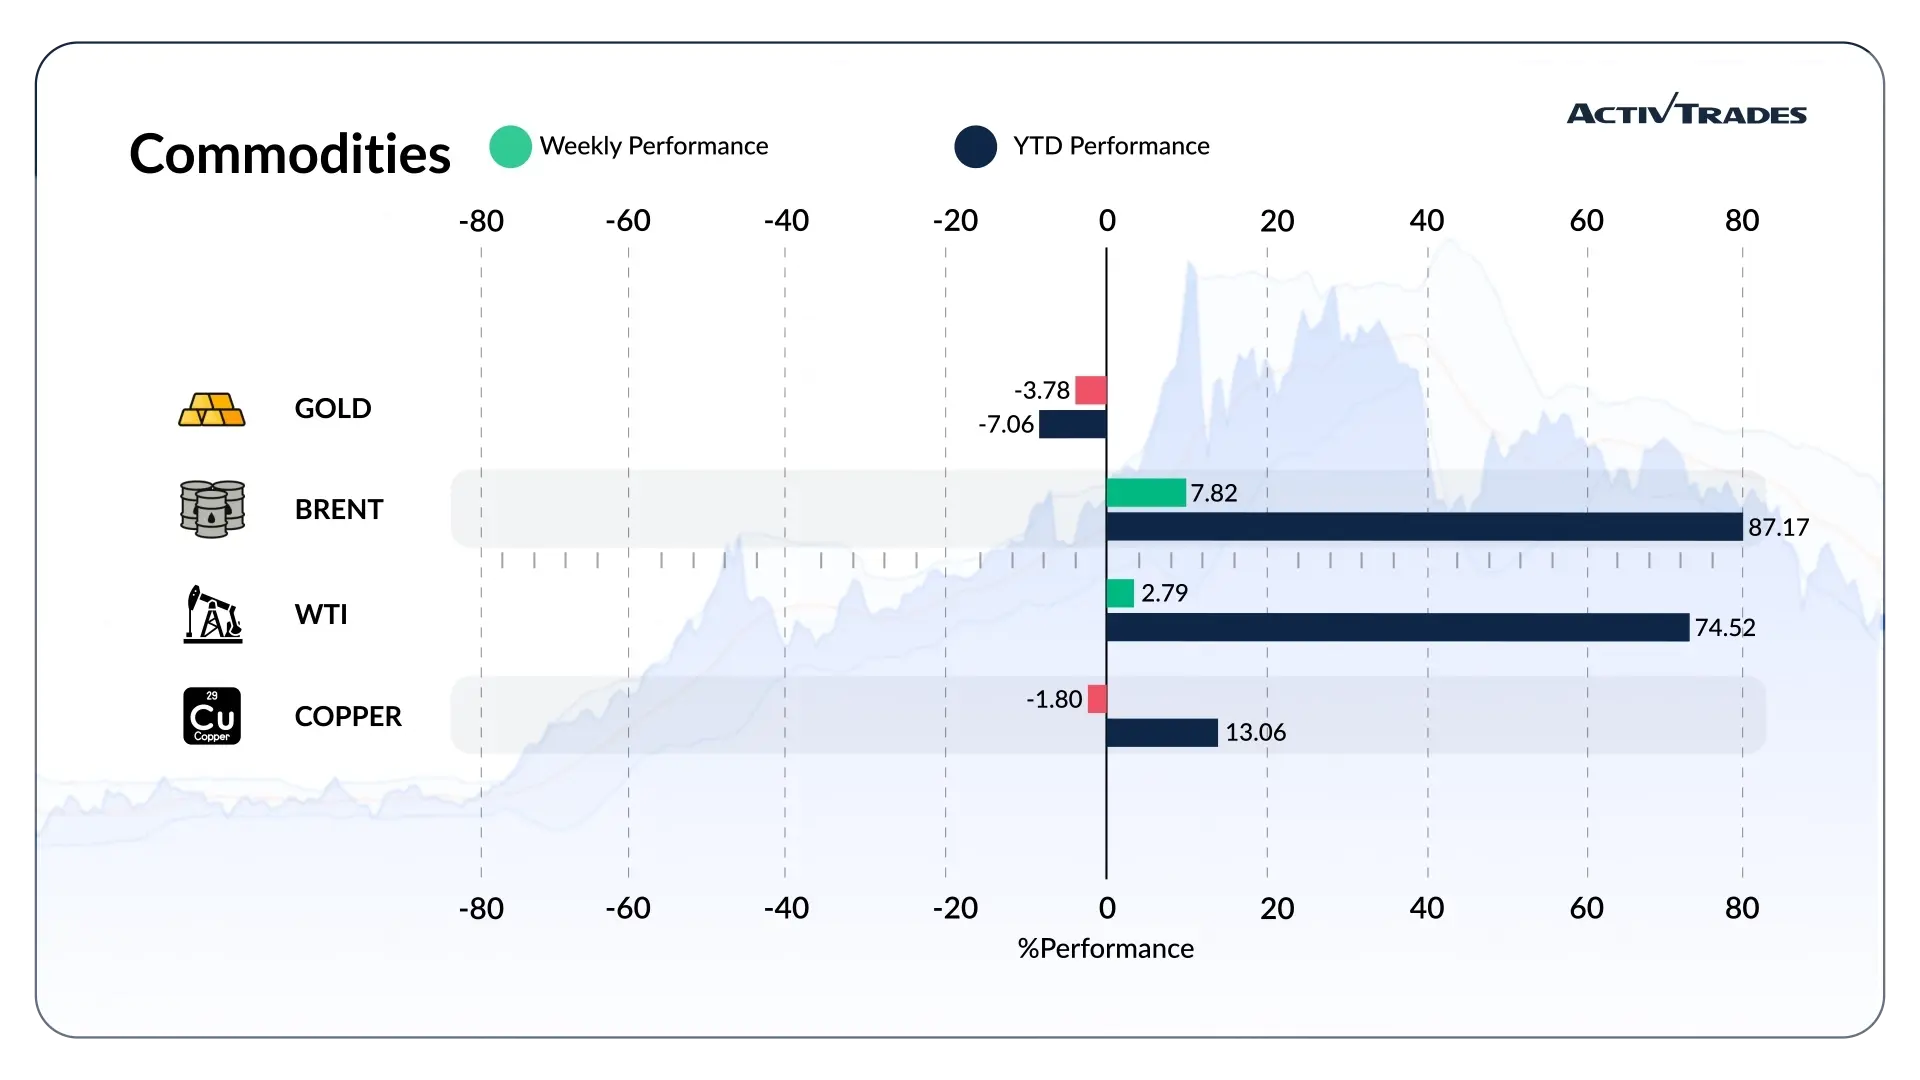
- London Gas Oil prices are up more than 5.2%.
- Dutch TTF Natural Gas prices are up more than 4%.
- Brent prices are up more than 3.8%.
- Nickel prices are up more than 3.3%.
- Natural Gas prices are down more than 12.2%.
- Palladium prices are down more than 5.6%.
- US Wheat prices are down more than 5%.
- Silver prices are down more than 4.9%.
Indices
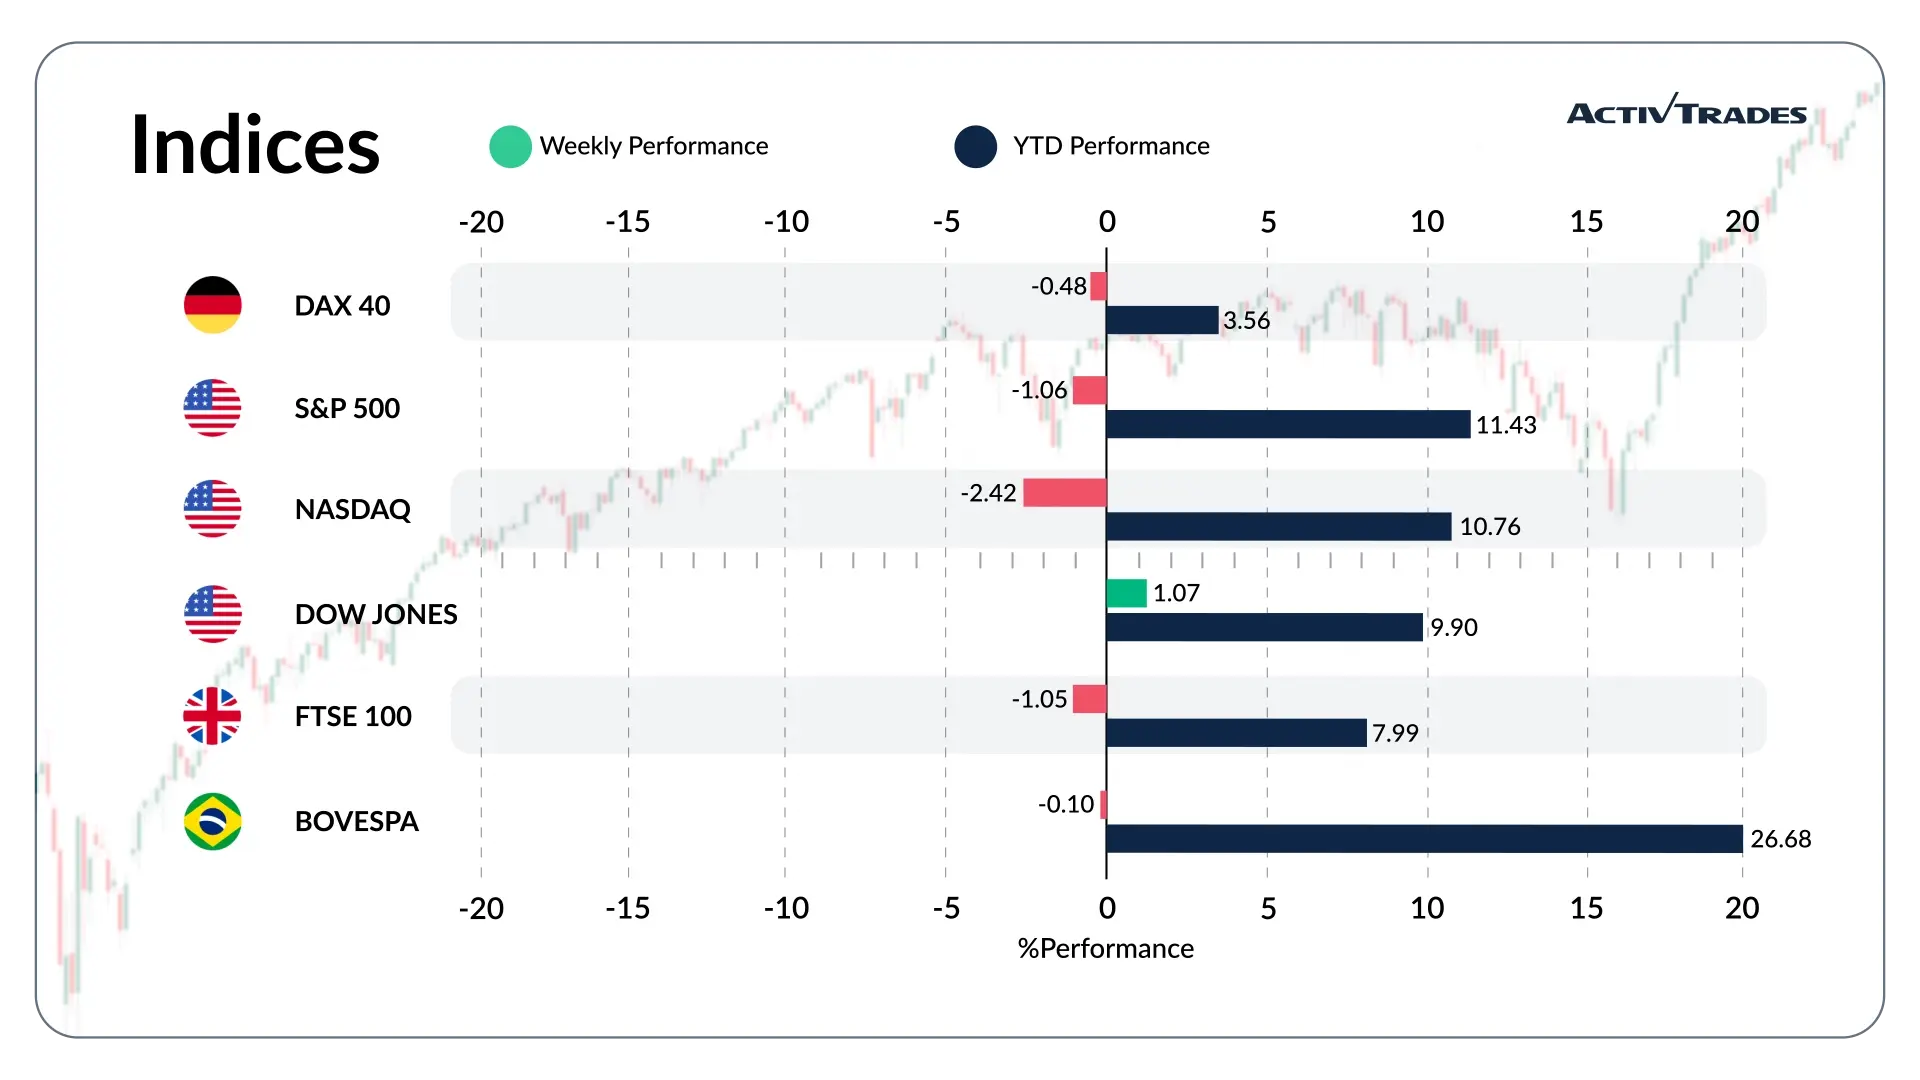
- The VIX index is up more than 8.4%.
- The S&P/BMV IPC index is up more than 4.4%.
- The Bist100 index is down more than 6.9%.
- The Shenzhen Component index is down more than 4%.
- The Japan 225 index is down more than 3.6%.
Shares
Tops
- Essilor Luxottica: +19.13%
- Hasbro: +19.12%
- Pool: +16.61%
- Equifax: +16.05%
- Accenture: +15.04%
- Ropper Technologies: +14.06%
- Epam Systems: +13.42%
- Allegion: +13.34%
- Gartner: +13.09%
- Thomson Reuters: +12.61%
- Cognizant: +12.09%
Flops
- Coreweave: -20.22%
- Carrefour: -17.81%
- Lam Research: -17.05%
- Nebius: -15.52%
- KLA: -15.26%
- Astera Labs: -14.62%
- Moderna: -14.32%
- ARM: -14.17%
- Quanta Services: -13.98%
- Confort Systems USA: -13.63%
- Lumentum: -13.46%
Important Events to Follow
Monday 26 October
- 09:00 AM - German - Ifo Business Climate (October)
- Previous: 9
- Forecast: 89.2
Tuesday 27 October
- 12:30 PM - American - Durable Goods Orders MoM (September)
- Previous: 0%
- Forecast: 0.6%
Wednesday 28 October
- 07:00 AM - German - GfK Consumer Confidence (November)
- Previous: -30.6
- Forecast: -32
- 01:45 PM - Canadian - BoC Interest Rate Decision
- Previous: 25%
- Forecast: 2.5%
- 01:45 PM - Canadian - BoC Monetary Policy Report
- 06:00 PM - American - Fed Interest Rate Decision
- Previous: 4%
- Forecast: 4.0%
- 06:30 PM - American - Fed Press Conference
Thursday 29 October
- 05:00 AM - Japanese - Consumer Confidence (October)
- Previous: 4
- Forecast: 6
- 12:30 PM - American - Core PCE Price Index MoM (September)
- Previous: 2%
- Forecast: 3%
- 12:30 PM - American - GDP Growth Rate QoQ Adv (Q3)
- Previous: 2%
- Forecast: 1%
- 12:30 PM - American - Personal Income MoM (September)
- Previous: 2%
- Forecast: 3%
- 12:30 PM - American - Personal Spending MoM (September)
- Previous: 9%
- Forecast: 3%
- 01:15 PM - European - Deposit Facility Rate
- Previous: 5%
- Forecast: 5%
- 01:15 PM - European - ECB Interest Rate Decision
- Previous: 65%
- Forecast: 65%
- 01:45 PM - European - ECB Press Conference
Friday 30 October
- 03:00 AM - Japanese - BoJ Interest Rate Decision
- Previous: 25%
- Forecast: 25%
- 06:30 AM - French - GDP Growth Rate QoQ Prel (Q3)
- Previous: 0%
- Forecast: 1%
- 06:30 AM - French - GDP Growth Rate YoY Prel (Q3)
- Previous: 5%
- Forecast: 4%
- 07:45 AM - French - Inflation Rate YoY Prel (October)
- Previous: 1%
- Forecast: 2%
- 08:00 AM - Spanish - GDP Growth Rate QoQ Flash (Q3)
- Previous: 7%
- Forecast: 6%
- 08:00 AM - Spanish - GDP Growth Rate YoY Flash (Q3)
- Previous: 6%
- Forecast: 6%
- 09:00 AM - German - GDP Growth Rate QoQ Flash (Q3)
- Previous: 3%
- Forecast: 0%
- 09:00 AM - German - GDP Growth Rate YoY Flash (Q3)
- Previous: 1%
- Forecast: 0%
- 10:00 AM - European - GDP Growth Rate QoQ Flash (Q3)
- Previous: 6%
- Forecast: 3%
- 10:00 AM - European - GDP Growth Rate YoY Flash (Q3)
- Previous: 2%
- Forecast: 1%
- 01:00 PM - German - Inflation Rate YoY Prel (October)
- Previous: 3%
- Forecast: 5%
Major Earnings Reports to Watch
Monday 26 October
- VERIZON
- Galp Energia
- Universal Health Services
Tuesday 27 October
- COCA-COLA
- BOEING
- ORANGE
- Novartis
- United Parcel Service
- VISA
- PayPal
- Ferrovial
- Seagate Technology
- HSBC
- Beiersdorf
- CMS Energy
Wednesday 28 October
- Aon
- Ford Motor
- Banco Santander
- Alphabet
- Dassault Systemes
- T-Mobile US
- BNP Paribas
- GLAXOSMITHKLINE
- Nomura
- Airbus
- MICROSOFT
- Deutsche Bank
- Chipotle Mexican Grill
- UBS Group
- Endesa
- AENA
- BIOGEN
- BASF
- Banco Comercial
- Jeronimo Martins
- Stellantis
Thursday 29 October
- Mondelez
- Starbucks
- Cognizant Technology Solutions
- Altri
- INTEL
- Total
- STMicro
- Repsol
- First Solar
- LLOYDS BANKING
- Adidas
- Advanced Semiconductor Engineering
- AMAZON
- Altria
- Mastercard
- ING GROEP
- Banco Bilbao Vizcaya Argentaria
- Société Générale
- TechnipFMC
- Prysmian
- Anheuser-Busch InBev
- SHELL
- CATERPILLAR
- Merck
- Gilead Sciences
- Eli Lilly & Co
Friday 30 October
- ASTRAZENECA
- CaixaBank
- Intesa Sanpaolo
- Sanofi
- Regeneron Pharmaceuticals
- PUMA
- Dominion Energy
- WisdomTree
- Credit Agricole
- EXXON MOBIL
- CHEVRON
- Abbvie
- Colgate-Palmolive
- NATWEST
- BP
Source: The Wall Street Journal, Investing, Trading Economics Calendar GMT, Reuters, TradingView and ActivTrades’ Data as of October 23, 2026
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and as such is to be considered to be a marketing communication.
All information has been prepared by ActivTrades (“AT”). The information does not contain a record of AT’s prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance is not a reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acting on the information provided does so at their own risk. Forecasts are not guarantees. Rates may change. Political risk is unpredictable. Central bank actions may vary. Platforms’ tools do not guarantee success.