Weekly Outlook
What Happened This Week?
United States
● Anthropic ANT shares were up 17% at the close of their first trading day, closing at $97.17 per share.
● Almost all Federal Reserve officials at the October meeting considered further interest-rate increases necessary to bring inflation under control. Some warned that delaying action could allow price pressures to become entrenched or force more aggressive tightening later. Others were prepared to support a pause only if markets understood that additional hikes remained likely.
● St. Louis Fed President Alberto Musalem said several more rate increases may be needed before next spring, arguing that resilient demand and persistent supply pressures risk keeping inflation elevated. Investors broadly expect another hike at the Fed’s December meeting, with tightening potentially extending into 2027.
● Moody’s Ratings said the U.S. economy has performed better than previously anticipated, with third-quarter GDP expanding at an annualized 3.4%. It forecasts full-year growth of 2.3% this year, slowing to 2% in both 2027 and 2028 as higher borrowing costs, expensive energy and a normalization in AI-related investment weigh on activity.
● The New York Fed’s manufacturing index dropped to 7.8 in November from 25.5 in October, indicating a much slower pace of factory expansion. However, the employment component strengthened considerably, climbing to 18.1, its highest reading since June 2022.
● U.S. housing starts increased 9.9% in October to an annualized 1.309 million units, beating economists’ expectations of 1.25 million and standing 2.8% above the level recorded a year earlier. Building permits, however, fell 7.4% to 1.295 million, a sharper decline than anticipated.
● Initial jobless claims edged up to 203,000 in the week ending November 14. Continuing claims increased by 70,000 to just over 1.76 million in the week through November 7, while the average time required to find a new job reached 27 weeks, its longest level in more than a decade outside the pandemic.
● The Federal Reserve board approved a smaller budget for salary increases across its 12 regional banks. Employees have reportedly been told to expect annual raises of 1% next year, compared with 3% this year. However, the budget for incentive payments and retaining staff in high-demand roles was increased.
● Fed Governor Lisa Cook has declined to participate in a White House hearing concerning her potential removal unless changes are made to the panel and its procedures. Her lawyer has called for Kevin Hassett to be removed from the panel, arguing that the process risks producing a predetermined outcome. The hearing forms part of the administration’s efforts to meet Supreme Court conditions following an earlier judicial block on Cook’s dismissal.
● Fed Chair Kevin Warsh said central bank staff have started examining how artificial intelligence could transform the economy. He described leadership in AI as a strategic issue for U.S. economic and national power.
Eurozone / Germany
● Germany’s ZEW Indicator of Economic Sentiment rose by 7.5 points to 35.6 in November, reaching its highest level since February. The European Commission also raised its German growth forecast for this year to 1.3%, from 0.6%, pointing to stronger government spending and exports.
● ECB Vice President Boris Vujcic said Europe’s efforts to expand non-bank financing must be accompanied by safeguards for financial stability. He highlighted the risk posed by elevated valuations among AI-related companies and the possibility of a sharp market correction. Policymakers are also concerned that insufficient funding for higher-risk start-ups is leaving Europe behind the U.S. and China in the development of new technologies.
United Kingdom
● UK inflation accelerated to 3.6% in October from 3.5% in September, with higher energy costs linked to the conflict between the U.S. and Iran contributing to the increase. The latest figures could reinforce expectations that the Bank of England will soon deliver a second consecutive rate increase.
● The unemployment rate declined to 4.6% in the three months to September, from 4.7% in the previous reporting period. However, annual growth in average weekly earnings excluding bonuses slowed to 3.5%, compared with 3.7% previously. The combination of easing wage growth and still-elevated inflation leaves the BoE facing competing signals as it assesses further tightening.
● The Bank of England raised its key interest rate to 4% earlier this month, citing the risk that higher energy prices could feed through into broader inflation.
Canada
● Bank of Canada Governor Tiff Macklem announced that he will not seek to remain in the role after his seven-year term ends on June 2. The central bank’s board has begun the search for a successor, with a nomination expected by next spring. The appointment will require approval from Prime Minister Mark Carney.
● Canadian consumer prices rose 3.1% year-on-year in October, unchanged from September and slightly below economists’ 3.2% forecast. Inflation therefore remains above the Bank of Canada’s 1%-3% target range. Excluding energy, prices increased by 2%, easing from 2.1% the previous month.
● Housing starts declined 2.2% in October to a seasonally adjusted annualized rate of 244,558 units, according to Canada Mortgage and Housing Corp. The six-month moving average also fell, slipping 1.7% to 246,231 units. Economic uncertainty, slower population growth and elevated borrowing costs are expected to keep housing activity subdued through year-end.
Japan
● Japanese consumer prices excluding fresh food increased 2.2% year-on-year in October, up from 2.1% in September. Another measure of underlying inflation accelerated to 2.1% in September from 1.7% in August, reinforcing expectations that the Bank of Japan could raise interest rates again in December.
● Governor Kazuo Ueda reiterated that the BoJ remains ready to increase borrowing costs further if necessary to keep underlying inflation anchored around its 2% target and prevent it from overshooting. He stressed the importance of maintaining price stability over the medium term.
● BoJ board member Hajime Takata argued that policymakers should adjust rates flexibly rather than follow a predetermined pace or size of increases. He had proposed lifting the policy rate to 1.5% at the October meeting, although the board ultimately maintained it at 1.25%. Markets are increasingly anticipating another increase in December.
Australia
● Australia’s unemployment rate climbed to 4.9% in October, its highest level since late 2021, after the economy shed 43,500 jobs. The weaker labour-market figures could strengthen the case for the Reserve Bank of Australia to leave interest rates unchanged. The Australian dollar fell to around 66.90 U.S. cents from approximately 67.20 cents following the release.
● Minutes from the RBA’s November meeting revealed a divided board, with six members supporting an increase in the cash rate to 4.85% and three opposing it. Policymakers agreed that further tightening could be necessary if inflation remains too high. The central bank does not currently expect inflation to return to its 2.5% target until mid-2028.
South Africa
● The South African Reserve Bank left its main repo rate unchanged at 7.25%, citing uncertainty in the global outlook and stronger-than-expected domestic inflation. Governor Lesetja Kganyago also highlighted persistently weak fixed investment.
● Headline inflation accelerated to 5.2% in October from 4.5% in September, largely reflecting higher fuel prices. The latest increase adds to the challenge facing policymakers as they balance inflation risks against domestic economic conditions.
Indonesia
● Bank Indonesia raised its benchmark seven-day reverse repo rate by 25 basis points to 6%, seeking to support the weakening rupiah and contain inflation. Governor Destry Damayanti described the move as a pre-emptive measure to keep price growth within the central bank’s target range.
This Week’s Market Movers
Forex
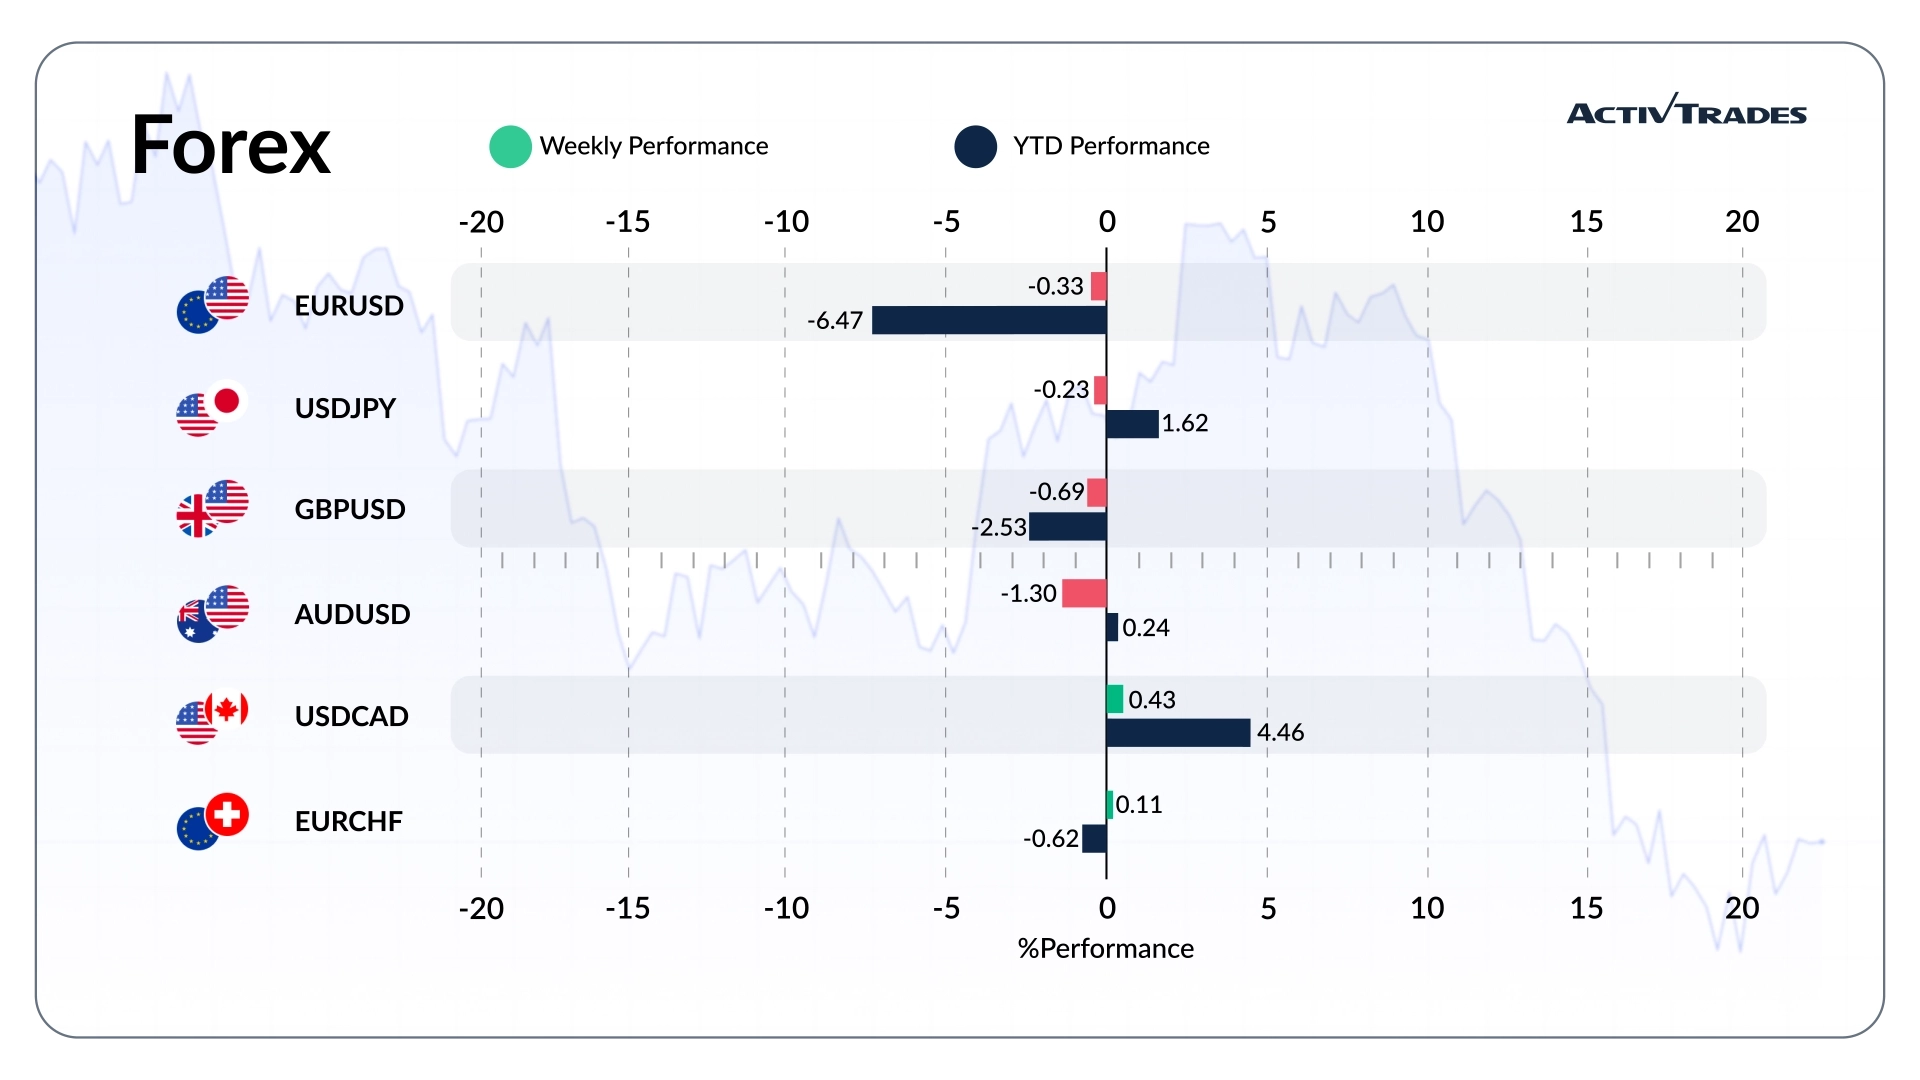
● The USD/BRL is up more than 5.2%.
● The USD/ZAR and the EUR/ZAR are up more than 4%.
● The JPY/AUD is up more than 2.4%.
● The CAD/AUD is up more than 1.5%.
● The JPY/CHF and the EUR/AUD are up more than 1.4%.
● The USD/CHF is up more than 0.9%.
● The USD/CAD is up more than 0.4%.
● The ZAR/JPY is down more than 4.5%.
● The MXN/JPY is down more than 3%.
● The GBP/JPY is down more than 1.3%.
● The AUD/USD is down more than 1.9%.
● The GBP/USD is down more than 0.8%.
Commodities
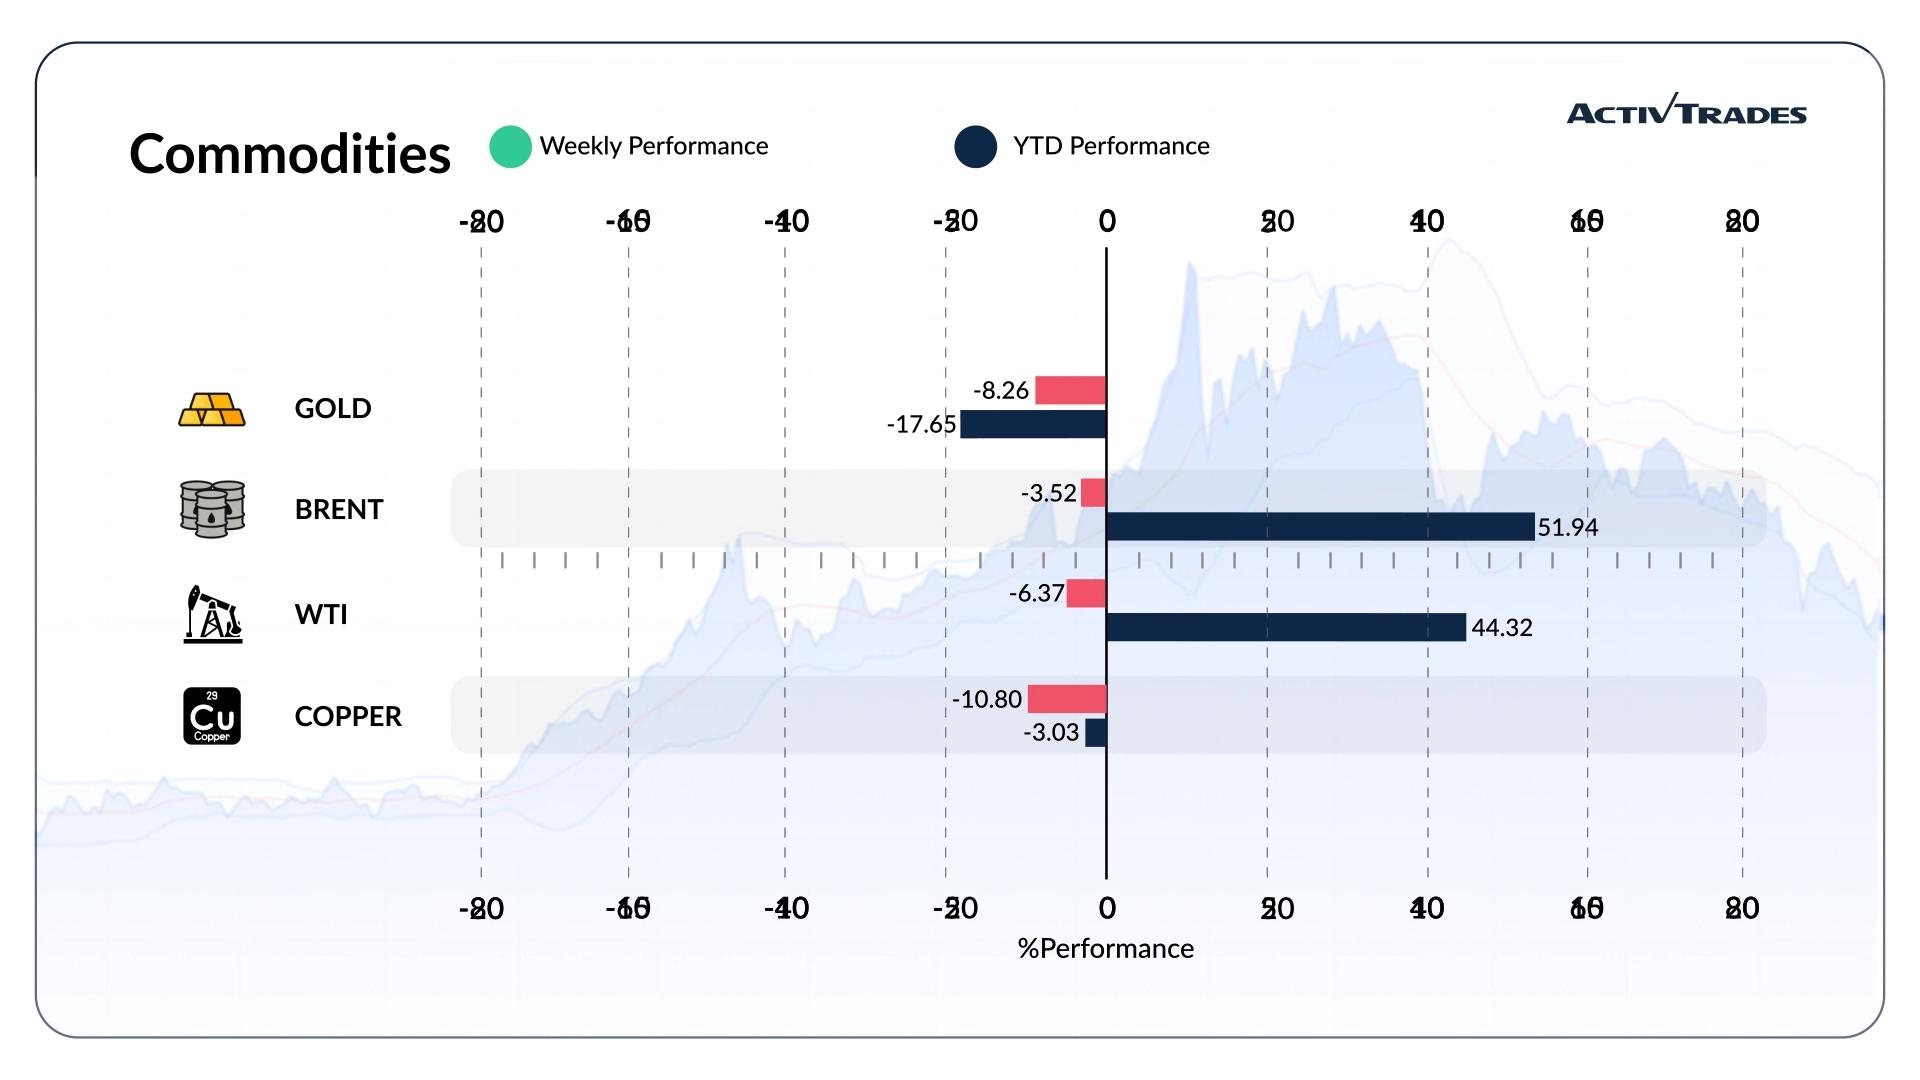
● Lumber prices are up more than 8.6%.
● Rough Rice prices are up more than 3%.
● Silver and XAG/USD prices are down more than 14%.
● Platinum and Palladium prices are down more than 12%.
● Copper prices are down more than 9.4%.
● Gold prices are down more than 8.5%.
● London Gas Oil prices are down more than 8%.
Indices
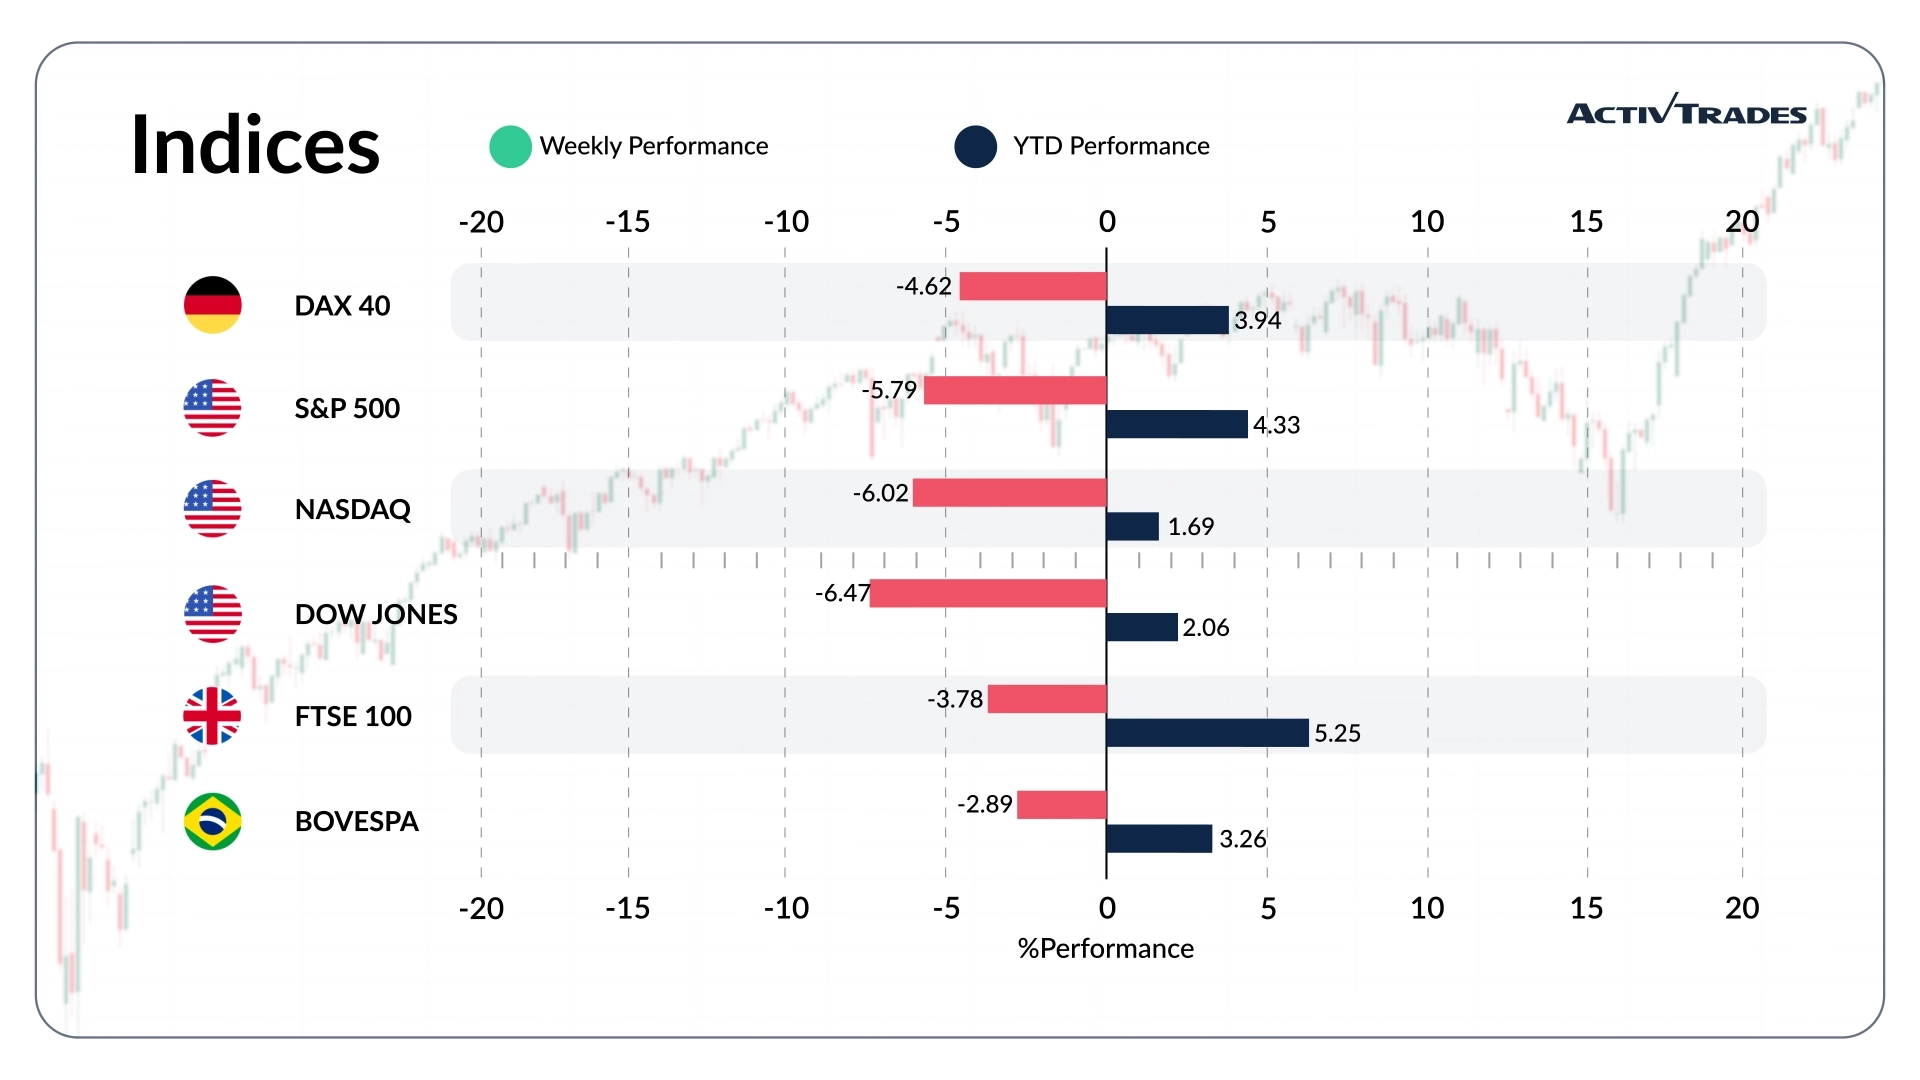
● The VIX index is up more than 54.9%.
● The Kospi index is down more than 10.6%.
● The Shenzhen Component index and the SA40 index are down more than 8.3%.
● The Japan 225 index is down more than 7.8%.
● The Dow Jones Industrial Average index is down more than 6.3%.
● The DAX index is down more than 5.3%.
● The SP500 index is down more than 4.9%.
Shares
Tops
● Palo Alto: +12.11%
● PDD: +10.92%
Flops
● Strategy: -24.72%
● Nebius: -24.66%
● Coreweave: -20.65%
● Rocket Lab: -20.42%
● Freeport-Mcmoran: -18.74%
● Unitedhealth: -18.43%
● Coinbase Global: -16.68%
● Skydance: -16.47%
● AMD: -16.42%
● Salesforce: -15.75%
● SAP: -12.01%
● Dassault Systems: -10.16%
Important Events to Follow
Monday 23 November
● 08:15 AM - French - S&P Global Composite PMI Flash (November)
○ Previous: 46.6
○ Forecast: 46
● 08:15 AM - French - S&P Global Manufacturing PMI Flash (November)
○ Previous: 49.5
○ Forecast: 49
● 08:15 AM - French - S&P Global Services PMI Flash (November)
○ Previous: 46.2
○ Forecast: 45.9
● 08:30 AM - German - S&P Global Manufacturing PMI Flash (November)
○ Previous: 54.2
○ Forecast: 53.8
● 08:30 AM - German - S&P Global Composite PMI Flash (November)
○ Previous: 53.4
○ Forecast: 52.9
● 08:30 AM - German - S&P Global Services PMI Flash (November)
○ Previous: 52.5
○ Forecast: 52
● 09:00 AM - European - S&P Global Composite PMI Flash (November)
○ Previous: 51.7
○ Forecast: 51.5
● 09:00 AM - European - S&P Global Manufacturing PMI Flash (November)
○ Previous: 52.7
○ Forecast: 52.2
● 09:00 AM - European - S&P Global Services PMI Flash (November)
○ Previous: 51.4
○ Forecast: 51.1
● 09:30 AM - UK - S&P Global Manufacturing PMI Flash (November)
○ Previous: 52.8
○ Forecast: 52.5
● 09:30 AM - UK - S&P Global Services PMI Flash (November)
○ Previous: 52.8
○ Forecast: 52.5
● 02:45 PM - American - S&P Global Composite PMI Flash (November)
○ Previous: 55.9
○ Forecast: 55.6
● 02:45 PM - American - S&P Global Manufacturing PMI Flash (November)
○ Previous: 54.9
○ Forecast: 54.5
● 02:45 PM - American - S&P Global Services PMI Flash (November)
○ Previous: 56.1
○ Forecast: 55.7
Tuesday 24 November
● 12:30 AM - Japanese - S&P Global Manufacturing PMI Flash (November)
○ Previous: 53.3
○ Forecast: 52.9
● 12:30 AM - Japanese - S&P Global Services PMI Flash (November)
○ Previous: 51.7
○ Forecast: 51.6
● 09:00 AM - German - Ifo Business Climate (November)
○ Previous: 90.2
○ Forecast: 90.1
Wednesday 25 November
● 01:30 PM - American - Core PCE Price Index MoM (October)
○ Previous: 0.3%
○ Forecast: 0.3%
● 01:30 PM - American - Durable Goods Orders MoM (October)
○ Previous: 1.8%
○ Forecast: 0%
● 01:30 PM - American - GDP Growth Rate QoQ 2nd Est (Q3)
○ Previous: 2.2%
○ Forecast: 3.4%
● 01:30 PM - American - Personal Income MoM (October)
○ Previous: 0.2%
○ Forecast: 0.2%
● 01:30 PM - American - Personal Spending MoM (October)
○ Previous: 0.5%
○ Forecast: 0.4%
Thursday 26 November
● 07:30 AM - German - GfK Consumer Confidence (December)
○ Previous: -30.8
○ Forecast: -30
Friday 27 November
● 07:45 AM - French - Inflation Rate YoY Prel (November)
○ Previous: 3.4%
○ Forecast: 3.8%
Major Earnings Reports to Watch
Monday 23 November
● Hewlett Packard
● Zoom
Tuesday 24 November
● Dell
● Medtronic
● Dollar Tree
● Best Buy
Source: The Wall Street Journal, Investing, Trading Economics Calendar GMT, Reuters, TradingView and ActivTrades’ Data as of November 20, 2026
The information provided does not constitute investment research. The material has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and as such is to be considered to be a marketing communication.
All information has been prepared by ActivTrades (“AT”). The information does not contain a record of AT’s prices, or an offer of or solicitation for a transaction in any financial instrument. No representation or warranty is given as to the accuracy or completeness of this information.
Any material provided does not have regard to the specific investment objective and financial situation of any person who may receive it. Past performance is not a reliable indicator of future performance. AT provides an execution-only service. Consequently, any person acting on the information provided does so at their own risk. Forecasts are not guarantees. Rates may change. Political risk is unpredictable. Central bank actions may vary. Platforms’ tools do not guarantee success.